Article Reviewed by a licensed insurance professional: Sam Meenasian (CA dept of insurance license #0F75955).
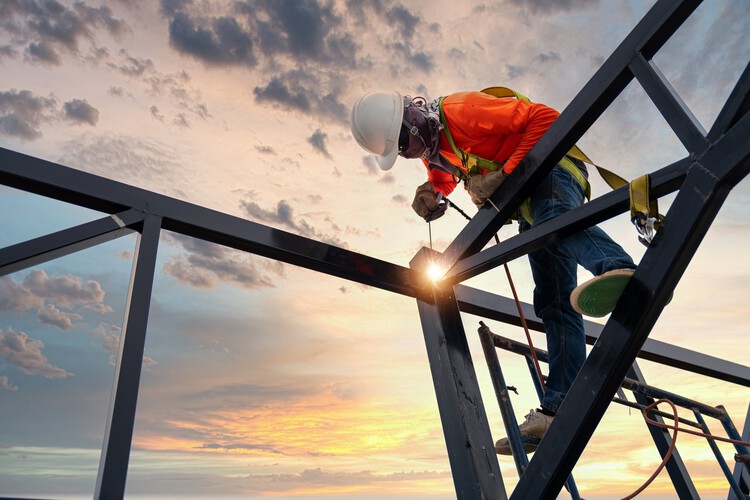
Welders will often talk about the risks of their job, and they might mention that sparks can lead to fire, but they rarely speak about this risk as if it will affect them. Many small business owners think they can fully control risk, so they are never affected by issues other businesses face.
Standard liability coverage may exclude damage caused by heating devices or hot work. This is often added to liability plans via an endorsement, which means most welding business owners are not even aware they lack access to this kind of protection for their company.
This isn’t something that small business owners who offer welding services should ignore. Fires are expensive to recover from, and the process of handling a claim is even more intensive when the fire happens on someone else’s property as a result of work that you are doing for them.
Heating Device Exclusions: How This Impacts Liability Policies
Insurance companies may classify the use of heating devices as a higher-risk work activity. This is because not every industry utilizes heating devices as part of their standard workflows.
Liability policies might exclude open-flame tools, welding torches, heat guns, hot plates or heaters, or soldering tools. This can vary by carrier, but there is a real need for those who offer welding services to ensure they are protected when using these tools as part of their daily workflows.
Welders often assume that if they have purchased liability coverage, it should specifically protect their type of business. This is not always the case, and welding professionals need to be aware of this common pitfall to avoid it.
Why Endorsements Work Well For Welders
Since standard liability insurance policies don’t always cover the use of heating devices, endorsements can be added to provide this coverage for welding professionals. This endorsement may cover losses resulting from sparks carried by the wind that start a fire, or from heat transferred through materials, depending on the policy terms.
The endorsement may also handle issues where heat from welding processes damages or warps nearby materials or surfaces, including existing materials that are not ideal to be exposed to heat. Solvents, fuel vapors, or even adhesives can be present where welding is being performed, and a welder might not realize it until a fire starts.
Welders Can Be Included in Claims They Didn’t See Coming
Welding is a profession that often requires working alongside people providing other services. Materials used during construction or remodeling jobs can be less than ideal when exposed to welding, but welders might not realize they are working in an area not fully prepared for welding.
While the claim could be for a fire caused by vapors in the home during a construction project, if welding is determined to have contributed to the loss, the welder could become part of the claims process, since the welding process could have helped cause the fire.
This is just one example, but it is a risk that welders are not always aware of in their field of work.
There are instances when welders might be involved in claims related to jobs that have closed, depending on the policy terms. This is one of the realities that can make it more complex for welders to obtain insurance, and it’s something welders should be prepared for.
What Else Does a Heating Device Endorsement Cover?
Your heating device endorsement may also cover smoke damage, scorching, melting of components or materials, blistering of paint, and damage from sparks, depending on the policy language. There are lots of other instances that might be covered in your policy, and you can verify which situations are covered by reading the fine print of your policy.
Even items that are near your welding equipment that aren’t full of solvents can become damaged by the heat generated while you work, and the cost of replacement of these items can be enough to require claims to be filed.
Heat Damage Claims Can Be Tough to Dispute
Heat damage claims can be complex to argue. These claims are investigated to determine where the heat originated, whether sparks migrated, whether the equipment used was appropriate for the job, and more.
You might not document all of these processes as you work, which can lead to issues with fault-finding and claim adjudication.
It’s key for welders to understand that even the slightest sign that sparks or heat might be affecting surrounding machinery or surfaces requires them to stop working and verify that things are okay. Being in the mindset that you won’t be held responsible for damages isn’t wise and can lead to costly issues that need to be resolved.
Some commercial contracts with welders may require that these endorsements be verified before work can begin, which means that you have more of a reason than ever to have the right coverage for your business. Even if you are a small business or a single operator, you need to carry the right coverage to protect your company from losses.
Shops that have items such as torches, cutting tables, portable heating tools, and other induction heating tools should also have this endorsement in place. Dry grass, dusty workspaces, old beams, flammable materials, and other items that you are not aware of are within the area that you are working and can all lead to fire damage or heat damage. Even a building specifically designated for welding can contain materials and items that can be damaged by your work processes.
The cost of your insurance may typically be far less than the cost of a claim, and this is key to remember.
Things to Remember
Your standard general liability policy might not provide coverage for heating devices. You need to remember that hot work and sparks can quickly lead to things like fires or heat damage. Welders can sometimes be implicated in the damage associated with a fire, and it can be hard to prove that your work processes didn’t start a fire after the fact. A heating device endorsement might be required to secure some jobs, and the cost of your policy may likely be much less than the cost of a claim.
USA Business Insurance offers support and guidance to businesses looking to put the right insurance protections in place to safeguard their investment. Reach out to us today for a quote and find out how we can help you to secure the coverage that you need for your small or mid-sized business.