Article Reviewed by a licensed insurance professional: Sam Meenasian (CA dept of insurance license #0F75955).
Estimated reading time: 7 minutes
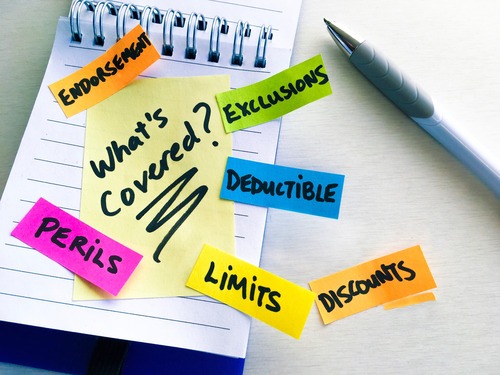
General liability is often sold as broad protection for contractors, but “broad” doesn’t mean unlimited. In contractor insurance, the real coverage story is often found in the endorsements, exclusions, and scheduled operations, not just the declarations page. Regulators and coverage experts alike emphasize reviewing classifications, exclusions, and endorsements for gaps because specific forms often narrow contractor policies by carving out the riskiest parts of the work.
That is an important distinction. In an unendorsed ISO CGL policy, class codes generally serve to rate exposure, not to automatically deny a claim. But once a carrier adds a classification limitation, designated work exclusion, or trade-specific endorsement, coverage can be restricted to only the operations the carrier intended to insure. That is why two contractors with the same trade label can have very different actual protection.
Tree Trimmers and Arborists
Tree work is one of the clearest examples of trade-specific underwriting. Tree-trimmer supplemental applications ask whether the contractor uses cranes, cherry pickers, or lifts; the maximum height; whether the business works for utilities; and what percentage of work is performed near utilities. Other tree and landscape applications ask whether crews climb trees, the maximum climbing height, and whether they perform any utility line clearance work. OSHA treats line-clearance tree trimming separately as specialized work around energized lines, and utility tree work providers note that utility line clearance requires different insurance and training than ordinary residential tree service.
For tree contractors, common GL trouble spots include height limitations, utility line-clearance exclusions, right-of-way work restrictions, storm-cleanup limitations, or requirements to move the account into a specialized tree program. A contractor that trims ornamental trees for homeowners faces fewer risks than a crew working near energized lines or clearing utility corridors. If any portion of the operation involves utility work, that exposure should be specifically disclosed and specifically addressed in the policy language.
Electrical Contractors
Electrical contractors can face significant coverage limitations when their work extends beyond standard interior wiring. Many underwriting guides define electrical contracting as installing and servicing wiring, fixtures, and electrical equipment within buildings, often limited to systems operating at or below approximately 480 volts. Work involving utility power lines, alarm monitoring services, or similar higher-risk operations is frequently considered outside the scope of that class.
Contractor supplemental applications commonly require detailed disclosure of operations such as solar panel installation, exterior electrical work, high-voltage systems, telecommunications or cable line installation, and underground activities, such as directional drilling or horizontal boring. These distinctions demonstrate how quickly underwriting eligibility and policy terms can change once electrical work moves beyond standard interior installations. For contractors, the practical takeaway is that expanding services into areas such as solar, telecommunications infrastructure, or underground utility work can trigger different classifications, additional underwriting review, or specific policy exclusions.
Roofers
Roofing is one of the most heavily restricted classes in contractor GL. Most policy forms exclude or sharply limit losses from open-roof, hot-application roofing operations or heat-processing equipment. Some forms preserve limited coverage only if the roofer follows specific jobsite controls, such as keeping a charged extinguisher on site, keeping personnel on site after hot work, and inspecting the work area before leaving.
Some roofing limitation endorsements may go further by excluding claims related to hot tar or other heated roofing materials, fires caused by heat applied during roofing operations, rain intrusion while a roof is open, or work performed above a specified height, such as more than three stories or 36 feet. In practical terms, a roofer should never assume that simply listing roofing on the policy automatically includes torch-down systems, kettle operations, temporary dry-in exposures, or water intrusion during construction. These operations often have endorsement restrictions and must be reviewed carefully before you bind coverage.
General Contractors
General contractors often assume their GL policy follows whatever project they manage. That assumption can be expensive. Some designated work forms list residential or commercial building and ground-up construction as ineligible contractor operations, and some endorsements specifically exclude new residential construction, except for narrow, checked exceptions. On top of that, insurance specialists warn that residential exclusions can be broad and may capture incidental residential work the contractor did not consider material to the account.
The key issue for general contractors is that new construction and residential are often defined more broadly than expected. A form can sweep in apartments, condominiums, townhomes, and tract housing, as well as related site or infrastructure work. So, a contractor that mainly does commercial remodel work but occasionally takes on ground-up or habitational projects should not rely on the class name alone. The project mix has to match the policy language before the bid goes out and before the contract is signed.
Concrete contractors
Concrete is another trade in which the accepted scope of operations is often narrower than the insured expects. Some forms of underwriting guides separate ordinary concrete work from foundation work, foundation repair, slab lifting or repair, public street or roadwork, and new residential construction. One designated work form lists concrete pouring and foundation work, as well as slab lifting or repair work, as ineligible. Another contractor guide permits certain concrete operations but deems foundation repair and new residential construction ineligible.
For concrete contractors, the biggest blind spot is often the shift from flatwork to structural or below-grade work. Patios, sidewalks, and driveways don’t carry the same exposure as footings, foundations, repair work, or work tied to soil movement. Insurance specialists also note that subsidence and earth-movement exclusions are particularly severe for contractors engaged in foundation construction, excavation, or other earth-moving work. If the contractor touches foundations, review that restriction alongside the trade-specific exclusion language.
Alarm Installers and Low-Voltage Contractors
Alarm and low-voltage work is a classic example of why installation coverage does not automatically mean service liability coverage. A contractor’s scope of work may include low-voltage electrical work and alarm installation but specifically exclude monitoring of alarm systems. A court summary involving a security company likewise describes GL and umbrella policies that contained alarm exclusions and notes that burglar and fire alarms required separate applications.
The practical lesson is simple. Installing devices is not the same risk as monitoring signals, dispatching a response, or taking on ongoing life-safety obligations. Contractors that sell or subcontract monitoring should treat that as a separate coverage conversation, not as a detail that will automatically ride inside the installer’s GL form. If the revenue comes from recurring monitoring, the policy should state that clearly, or the contractor should assume a gap until proven otherwise.
Fiber optic and communications contractors
Fiber optic contractors can move from relatively straightforward installation work into much tougher coverage territory as soon as underground utility work or directional boring comes into play. Supplemental applications ask for the percentage of telephone or cable line work performed underground versus aboveground, the type of line involved (including fiber-optic lines), and the methods used (including directional drilling). Utility contractor applications also ask for the percentage of directional drilling or boring and the controls used to mark underground lines and review utility drawings before the job starts.
That underwriting focus reflects a real loss exposure. OSHA warns that horizontal directional drilling can strike existing underground electrical, water, sewage, gas, steam, or chemical lines. On the policy side, ISO also has an underground resources and equipment exclusion form that removes coverage for certain underground damage exposures. For a fiber contractor, the real question is not simply, “Do you install cable?” It is: Do you trench, bore, or directionally drill, and if so, does the policy still cover underground utility damage?
What should contractors do before binding coverage?
Before binding a contractor GL policy, get the declarations plus every endorsement, not just a quote summary. Compare the scheduled operations to actual payroll and revenue by trade. Then review whether the form includes any classification limitation, designated work exclusion, residential or new construction restriction, height or story limitation, open-roof or hot-work limitation, underground exclusion, subcontractor warranty, or contractual liability limitation. When a carrier treats an exposure as separate, such as solar, alarm monitoring, utility line work, or directional drilling, do not assume the base GL form automatically covers it. Ask for confirmation in writing.
The cheapest general liability policy is rarely the best one if it excludes the work that produces most of the contractor’s revenue. In contractor insurance, the exclusion endorsement often tells you more than the declarations page. The safest approach is full operational disclosure, exact classing, and a line-by-line review of endorsements before work begins.